
Sanctions aimed at squeezing Moscowâs revenues have instead helped drive up prices, making Russian crude more valuable
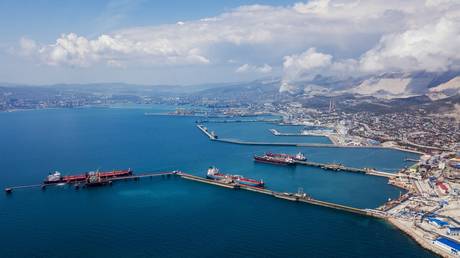
Nearly four years after Western governments set out to squeeze Russia’s oil revenues, Moscow is shipping crude worth more per week than at any point since the escalation of the Ukraine conflict in 2022.
The gross value of Russia’s seaborne crude exports surged to $2.75 billion in the week through September 27, the highest weekly figure in four years, according to tanker-tracking data compiled by Bloomberg. Shipments averaged 3.71 million barrels per day over the latest four weeks, their highest since early August.
The rebound exposes a central problem with the Western strategy. Sanctions were designed to keep Russian oil on the global market to avoid a supply shock while forcing Moscow to sell it more cheaply.
Instead, Russia rerouted crude from Europe to China, India, and other markets, built alternative shipping networks, and reduced its reliance on Western services. Now, soaring global prices fueled by the US-Israeli war on Iran are making those barrels more valuable.
The plan: Keep Russian oil flowing but slash Moscow’s earningsWhen the West moved against Russian oil in 2022, it faced an obvious problem: Russia was too large an exporter to remove from the market without risking a surge in global prices.
The EU was also Moscow’s biggest oil market. Europe took more than half of Russia’s oil exports in 2021, while Russia was the EU’s largest crude supplier, accounting for roughly a quarter of its imports. China, by comparison, was Russia’s largest single-country buyer.
The EU banned most seaborne Russian crude imports in December 2022, while the G7-led bloc imposed a $60-per-barrel price cap. Western shipping, insurance, and other maritime services could still handle Russian crude, but only if it was sold below the ceiling. Sanctions on petroleum products followed in February 2023.
The logic was simple: cut Russia’s revenues without removing its oil from the global market. The strategy therefore depended on keeping Russian crude flowing while using Western dominance of shipping and insurance services to constrain its price.
The plan backfired.
What went wrong?The $60 cap initially coincided with steep discounts on Russia’s flagship Urals crude. But Moscow gradually reduced its dependence on Western shipping and insurance services by which the ceiling was supposed to be enforced.
Even the Centre for Research on Energy and Clean Air (CREA) – a Helsinki-based research organization that has repeatedly advocated tougher sanctions on Moscow – now says the policy has failed to impose a durable constraint on Russian crude export earnings. It says the measure worked only for limited periods on Urals, while other grades and export channels were largely unaffected.
The EU repeatedly tightened the mechanism, lowering the ceiling first to $47.60 and then to $44.10 per barrel from February 2026. The latter was intended to remain 15% below the average market price for Urals.
Yet Urals averaged $60.22 a barrel in July – roughly $16 above the EU and UK ceiling. Russia’s ESPO crude, heavily oriented toward Asian buyers, has also consistently traded above both the old and new caps, according to CREA.
Brussels has responded by sanctioning hundreds of tankers, targeting traders, and tightening restrictions on third-country entities accused of helping Moscow circumvent the measures. Russian crude, however, continues to flow.
Four years later: Where is Russian oil going?Russia did not stop selling oil when its biggest European customers turned away. It found other customers.
China and India emerged as the dominant destinations for Russian crude, while Türkiye also increased its role. In July alone, India imported $6.25 billion worth of Russian crude – a record high for a second consecutive month – while seaborne deliveries to China